Strategic Decision or Structural Advantage?
Databricks data shows Anthropic dominating the high-end frontier token market while OpenAI aggressively captures low-end volume through massive price cuts.
Decoder
- Tokenomics: The economic study of how tokens are valued and utilized within a system, specifically here referring to API usage costs.
- SOTA: State-of-the-art; the most capable models currently available in terms of performance and intelligence.
Original article
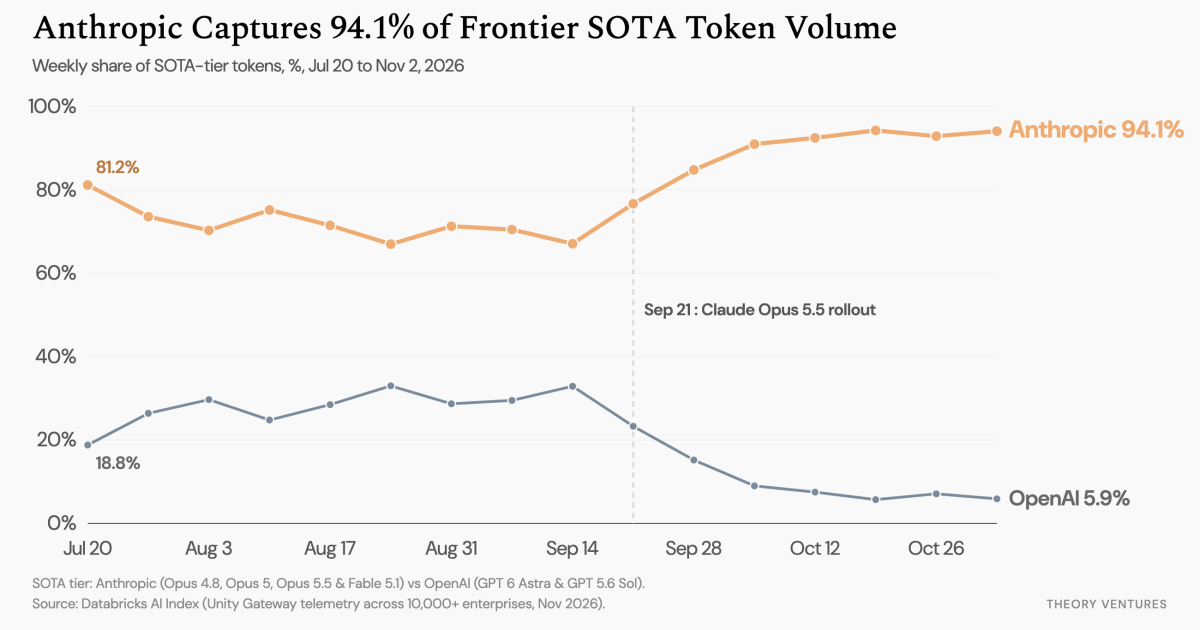
In short : Sixteen weeks of Databricks Unity Gateway telemetry across 10,000+ enterprises show Anthropic & OpenAI splitting the market by tier. Anthropic captures 94% of frontier SOTA tokens & 70% of proprietary spend, while OpenAI captures 81% of low-end tokens & coincides with open-weight share stalling at 31% after cutting Luna prices by 90%.
OpenAI & Anthropic each hold roughly 90% market share of an AI segment, but those segments are different : Anthropic holds dominant share at the premium end (94%), & OpenAI at the low end (81%).
Across 10,000+ enterprises, that split raises a business question : is this a deliberate pricing strategy to capture different ends of the market, or a structural cost difference in how the two labs serve tokens?
Anthropic sells a premium product & dominates the SOTA (state-of-the-art) tier. Anthropic’s share of SOTA token volume rose from 81% in July to 94% on November 2, propelled by the September 21 rollout of Claude Opus 5.5.
The mid tier is where the two labs now collide directly. Across all Sonnet & Sol versions (Sonnet 5 & 5.5 vs GPT-6 Sol & 6.1 Sol), OpenAI climbed from 0% in July to 47% of mid-tier volume by November 2, & took 57% of the newest Sonnet 5.5 vs Sol 6/6.1 cohort within six weeks of launch.
OpenAI pursued the opposite strategy, using aggressive price cuts on Luna to capture the high-volume floor. On July 30, OpenAI cut Luna pricing by 80% & then another 50% just a few months later, for a 90% total reduction.
On September 22, OpenAI launched GPT-6 Luna at $0.10 per 1m tokens. Its low-end share surged from 30% to 66% after the first cut, peaked at 84%, & finished at 81% on November 2.
Open-weight token share climbed every week from 7% in July to 33% in September, then stalled at 31% in the same week GPT-6 Luna & Sol cut prices by 50%.
That raises the strategic question in foundation models today : is Luna’s pricing a short-term market-share subsidy, or a structural cost advantage in OpenAI’s model architecture?
Fresh dev news, AI-digested daily. Never miss a trend at devoured.fyi