A Change in AI Strategy
AI models are becoming commodities, pushing labs to prioritize UI control and task routing to capture value over simple benchmark performance.
Deep dive
- Frontier model market share dropped from 53% in August to the mid-40s as enterprise users favor cheaper, specialized models.
- High-volume adopters are shifting to niche routing models like TypeSafe’s Jev, which cost 75x less than standard LLMs.
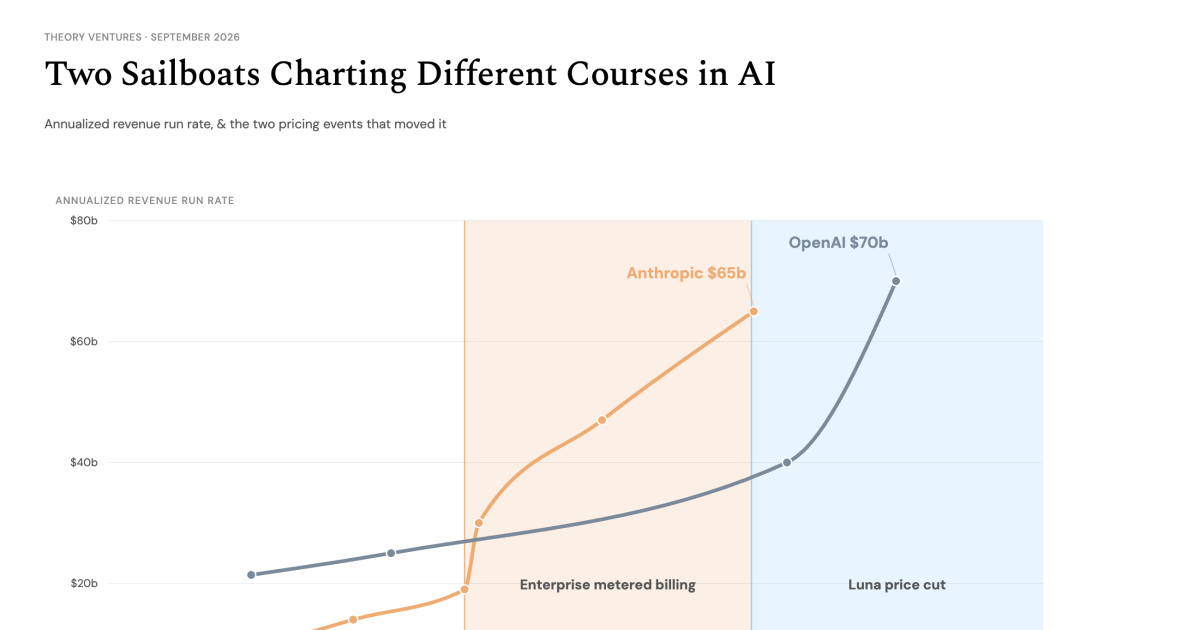
- OpenAI's $70 billion revenue run rate is increasingly driven by marketplace aggregation and aggressive pricing rather than just model supremacy.
- The new moat for AI companies is the user interface and distribution channel, not the model weights themselves.
- Companies are increasingly using 'routing'—sending specific tasks to the most efficient model—to maximize cost-effectiveness.
Decoder
- Router (LLM): A specialized, lightweight model or system that categorizes a user prompt and directs it to the most cost-effective or accurate LLM for that specific task.
- Commodity status: A market condition where a product is perceived as identical to competitors, causing price to be the primary differentiator.
- Harness: A user-facing application layer that wraps LLM calls, designed to keep users within a specific ecosystem.
Original article
In short : AI models have reached commodity status as prices fall 41% while token usage surges 50%. To win relative share, labs should partner & resell models, control the user interface where distribution becomes the moat, & capture routing data to reduce the cost of training future models.
What if AI models have just reached commodity status? In early 2025, we debated whether labs would become the airlines of the AI industry : high cost, low margin businesses with undifferentiated products.
Over the past month, the evidence has mounted :
- OpenAI cut prices on Luna by more than 80% to win share.
- Frontier models’ share of tokens slipped from 53% in August into the mid-40s as companies defaulted to smaller, cheaper tiers.
- Open source demand has shifted decisively from frontier-dominated to medium-&-small tiers.
- Spending among the top 1% of adopters fell 9.7% in August to $7,205 per employee per month, cooling from its July peak.
- Decision models like TypeSafe’s Jev are winning share of LLM calls at $0.04 per million input tokens, roughly 75x cheaper than standard LLMs for routing, gating, & classification.
Throughout all this, token usage has surged 50% since July, while prices have fallen 41%.
What’s the strategy in this environment?
First, partner. OpenAI announced a partnership with Baseten to resell open-weight models. Elon tweeted that the Grok bot would use the best model to complete a task, not just SpaceXSI models. Reselling produces a new, high-margin revenue stream by collecting a toll on products without bearing the cost to serve.
No company can provide the best model for every use case. Maximizing customer attention & retention is the most valuable asset in a commodity market.
Second, control the user interface. Distribution has become the moat. Build great harnesses that demand a lot of tokens : give them mononyms like Dots, Bot, & Muse to retain users. Also provide the best models for the job so people stay. This suggests ads & commerce as an important revenue driver for the B2C market.
Third, capture user data for intelligent routing & training infrastructure. Reselling other models while routing tasks across them aggregates a tremendous amount of information useful for subsequent model training.
Winning share becomes the only game that matters when aggregate dollar spend cools while token volume compounds. This means controlling the user interface.
OpenAI’s recent surge toward a ~$70b run rate highlights the dynamic : aggressive price cuts & marketplace aggregation allowed it to recapture share within a boat length of Anthropic.
In a commoditizing market, the spoils do not accrue to the lab with a marginal benchmark lead, but to the platform that aggregates the volume.
Fresh dev news, AI-digested daily. Never miss a trend at devoured.fyi